
Local Bank Transfers and Their Role in Philippines Online Betting
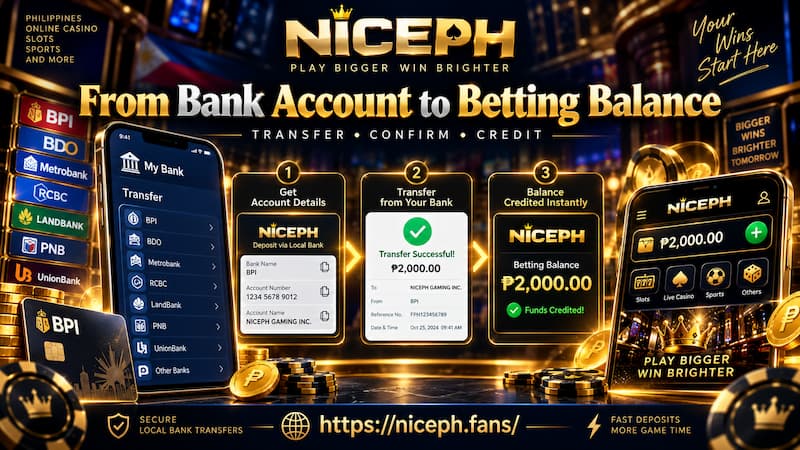
Local bank transfers can look simple from the user’s side: enter the recipient, choose an amount, confirm the transaction, and wait for the bank to report success. For an online betting account, however, that confirmation covers only one part of the process. The funds may still need to reach a receiving account or payment processor, be matched to the correct user, and then be credited to the betting balance.
Understanding those separate stages makes bank-transfer deposits easier to manage. It also explains why a transaction can appear successful inside a banking app while the corresponding betting balance is still pending.
A Betting Deposit Has Several Processing Stages
A local bank deposit should not be treated as one single event. In practice, several systems may participate before the money becomes usable inside the betting account.
A typical transaction can pass through the following stages:
- The player submits a transfer through the sending bank.
- The transaction moves through the selected payment rail.
- The receiving bank or payment processor accepts the funds.
- The incoming payment is matched to the relevant betting account.
- The amount is posted to the user’s betting balance.
These stages do not necessarily finish at the same time. A bank may complete the transfer quickly while the receiving system still needs to identify the transaction or complete internal processing.
Bank Success Does Not Always Mean Betting Credit
This distinction is especially important when checking a delayed deposit. A “successful” or “completed” status inside a banking app confirms that the banking instruction has been processed, but it does not automatically confirm that the betting cashier has finished its side of the transaction.
Before assuming that a deposit has failed, it is useful to distinguish between a transfer that has not reached the receiving institution and one that has arrived but is still waiting for account matching or internal crediting.
InstaPay and PESONet Follow Different Timing Models
InstaPay and PESONet are major electronic fund-transfer services under the Bangko Sentral ng Pilipinas’ National Retail Payment System. Both can move money electronically between participating Philippine financial institutions, but they are designed around different settlement models.
InstaPay and PESONet Follow Different Timing Models
InstaPay for Time-Sensitive Transfers
InstaPay is designed for real-time, low-value electronic fund transfers. This makes it more suitable when the bank-side movement of money needs to happen quickly or when payment instructions are time-sensitive.
Real-time transfer does not necessarily mean real-time betting credit, however. Even after the receiving institution obtains the funds, the payment may still need to be identified and connected with the correct betting account.
A useful distinction is:
- InstaPay speed refers primarily to the movement of funds through the banking network.
- Betting credit speed also depends on the processor and cashier system recognizing the transaction.
The two can be closely connected without being identical.
PESONet Uses Batch Processing
PESONet processes transactions in batches rather than individually in real time. Under the BSP framework, settlement occurs through scheduled cycles during the business day, with receiving institutions crediting funds after the relevant clearing process.
For a betting deposit, timing therefore matters more when PESONet is used. A transfer submitted earlier in the banking day may behave differently from one made near a cut-off or outside the most convenient processing period.
Neither rail is automatically the correct option for every payment. The current cashier instruction, transfer amount, timing, and available banking methods should determine which one is appropriate.
Always Use the Current Deposit Instructions
One of the easiest ways to create a payment problem is to reuse old recipient information. Betting operators or payment processors may change receiving banks, account numbers, reference formats, transaction limits, or other details over time.
For PH33 or another online betting account, a safer bank-transfer process is:
- Open the current deposit or cashier page.
- Select the local bank-transfer option currently available.
- Check the recipient bank, account name, and account number.
- Enter the requested deposit amount.
- Add the reference or payment code if one is provided.
- Review all details before authorizing the payment.
- Save the bank receipt or transaction record.
- Keep the record until the betting balance has been credited.
The most important part of this process is using the instructions attached to the current transaction. A screenshot or recipient account that worked previously may no longer be valid.
Reference Matching Can Matter as Much as Transfer Speed
Once money reaches the receiving side, the cashier still needs to determine which betting account should receive it. Depending on the payment setup, that matching process may use the sender’s information, amount, transaction reference, payment code, or a combination of several details.
This is why a bank transfer can technically succeed but still require manual review. The banking system has completed its task, yet the cashier may not have enough information to identify the correct user automatically.
Small Errors Can Create Long Delays
Typical problems include:
- Missing or incorrect transaction references
- Using an outdated recipient account
- Entering the wrong transfer amount
- Sending to the wrong account number
- Duplicate transfers
- Sender information that differs from what the cashier expects
- Receipts that do not clearly show transaction details
A missing reference may look like a minor error to the sender, but it can change a fully automated deposit into a transaction that needs manual reconciliation.
Exact Amounts Should Not Be Changed Without Reason
Some payment systems may use a specific amount as part of the matching process. If the cashier displays an exact amount or special payment instruction, changing it can make automatic recognition more difficult.
The safest approach is therefore to follow the displayed instructions exactly rather than treating every betting deposit like a normal person-to-person bank transfer.
Keep the Transaction Receipt Until the Balance Updates
A payment receipt is important because it creates a traceable record of what was actually sent. It can help both the financial institution and the payment processor investigate a transaction if the balance fails to update normally.
A useful receipt should ideally show:
- Transaction or reference number
- Date and time
- Amount transferred
- Recipient information
- Sending institution
- Transaction status
Keep this information until the betting balance is visible and usable. A receipt proves that a transfer instruction was completed through the bank, but it does not by itself prove that the correct betting account has already been credited.
Keep the transaction record until the balance appears in the betting account, not only until the banking app reports a successful transfer.
Where a Pending Deposit Can Be Delayed
When a deposit remains pending, the delay can occur at more than one point. Identifying the likely stage is more useful than treating every problem simply as a “slow bank transfer.”
Where a Pending Deposit Can Be Delayed
Possible delay points include:
- The sending bank
- InstaPay or PESONet processing
- The receiving institution
- A third-party payment processor
- Automatic account matching
- Manual cashier review
For example, a player may send PHP3,000 through InstaPay and receive an immediate success notification from the bank. If the amount and reference match the current payment instruction, the cashier may recognize the transfer quickly. If the reference is missing, the bank can still have performed correctly while the betting balance remains pending until someone reviews the transaction manually. If it remains unresolved after the normal processing period, use PH33’s contact page and provide the transaction reference and receipt rather than sending a duplicate payment.
Fees and Limits Can Come From Several Places
Another common mistake is assuming that the betting cashier alone determines how much can be transferred. In reality, several independent limits or charges can apply to the same transaction.
Bank and Transfer Limits
The sender’s financial institution may impose daily or per-transaction limits, while the participating institution or transfer rail can have additional rules. These limits can vary depending on the bank, account type, or transaction channel.
Cashier Limits
The betting cashier or payment processor can separately set minimum and maximum deposit amounts. A player’s bank balance may therefore be sufficient even when the requested transfer falls outside the cashier’s accepted range.
Three different levels should be checked:
- The bank’s transfer limit
- The applicable transfer-rail or institutional limit
- The betting cashier’s minimum and maximum amount
Transfer charges can also differ between Philippine banks and financial institutions. BSP publishes information on InstaPay and PESONet fees because pricing is not identical across every provider or channel.
For small deposits, even a relatively small fixed charge can represent a noticeable percentage of the amount being transferred. The useful comparison is therefore the total transaction cost relative to the amount moved.
Withdrawals Do Not Follow the Same Path as Deposits
A withdrawal is not simply a deposit running in reverse. With a deposit, the player normally initiates the bank transfer first and the betting account receives the funds afterward. A withdrawal usually begins with a request inside the betting platform.
Before funds are sent to the banking network, the operator may need to:
- Receive the withdrawal request.
- Confirm account and banking information.
- Perform any required internal checks.
- Approve the transaction.
- Send the funds through the available banking channel.
This distinction explains why access to a fast transfer rail does not automatically guarantee a fast withdrawal from beginning to end.
Fast Banking and Fast Withdrawal Are Different
Once funds have actually been sent through an appropriate banking rail, the bank-side transaction may complete quickly. The total withdrawal time, however, also includes everything that happens before that point.
Withdrawal speed should therefore be judged from the moment the request is submitted until the money arrives, rather than only by the speed of the final bank transfer.
Check Recipient Details Before Confirming
Bank-transfer errors can require significant follow-up, so the final confirmation screen deserves more attention than it usually receives. BSP advises users to verify recipient information before completing an InstaPay transaction because mistaken transfers may require assistance from the financial institutions involved.
Before authorizing a betting deposit, check:
- Recipient account name
- Account number
- Transfer amount
- Payment reference or code
- Selected transfer method
This takes only a few seconds but can prevent a much longer tracing process later.
Payment Capability Is Not Proof of Operator Legitimacy
The existence of a working receiving bank account does not prove that an online gaming service is properly authorized. Banking access and gaming authorization are two separate issues.
PAGCOR launched PAGCOR Guarantee in June 2025 to help the public verify whether online gaming providers are legitimate. Users should perform that check independently rather than treating a bank account, QR code, payment processor, or functional cashier as evidence of regulatory approval.
This distinction is especially important because transferring money successfully only proves that the destination can receive funds. It does not establish the legal or regulatory status of the gaming service behind it.
Payment Controls Changed in 2025
The regulatory environment around gambling-related payments tightened in August 2025 when the BSP instructed supervised financial institutions to remove links that provided direct access to gambling services from mobile payment apps and websites. PAGCOR later referred to safeguards that included the delinking of e-wallets and certain payment channels.
That development should not be interpreted as meaning that every ordinary bank transfer was prohibited. Availability can depend on the financial institution, payment processor, operator, and current compliance arrangements.
For users, the practical rule is straightforward: rely on the payment options and instructions shown for the current transaction instead of an old screenshot, saved bank account, or outdated tutorial.
A Final Bank-Transfer Check Before Sending
Most avoidable payment problems can be reduced by checking five things before confirming the transaction:
- Destination: Is the recipient account the one currently displayed by the cashier?
- Amount: Does the amount exactly match the payment instruction?
- Reference: Has the required payment reference or code been entered correctly?
- Transfer method: Does the selected bank-transfer method fit the current instruction and timing?
- Record: Can the receipt be saved in case the payment needs to be traced?
This checklist is more useful than focusing only on whether a transfer method is described as fast.
Where Local Bank Transfers Fit in Online Betting
Local bank transfers can suit users who prefer a familiar banking interface, direct account-to-account movement, and a clear transaction record. InstaPay is more closely aligned with real-time bank-side transfers, while PESONet follows a batch-processing model that requires greater attention to settlement timing.
Neither method should be judged on transfer speed alone. The complete experience also depends on recipient accuracy, transaction references, fees, limits, cashier matching, and any processing required before a withdrawal enters the banking network.
That is the real role of local bank transfers in Philippines online betting. The banking system provides the financial rail, but a successful transaction still depends on using the correct destination, following current instructions, keeping accurate records, and understanding where bank processing ends and betting-account processing begins.